Trending
hong-kong
Source: Newsmaker.id
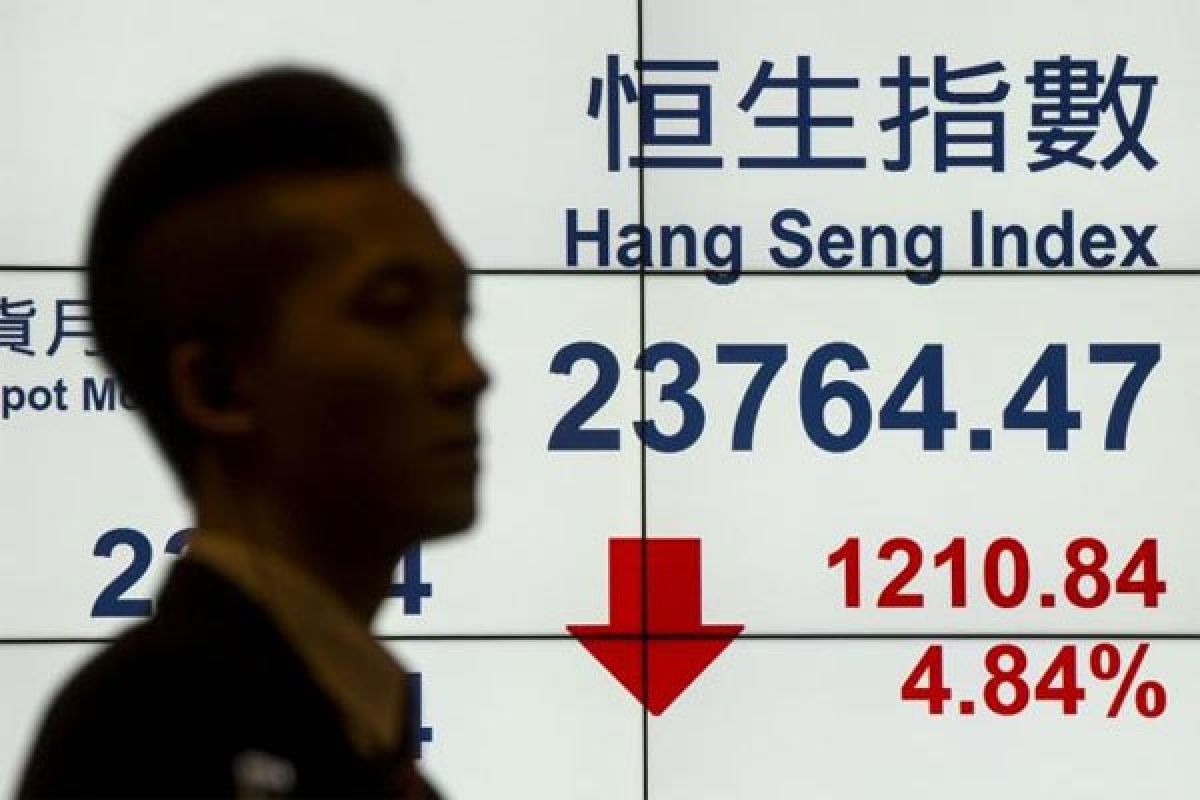
The Hang Seng Index closed lower in Monday's trading (Sept 7) after previously hitting a two-week high. Hong Kong's benchmark index fell approximately 0.9%, or 238 points, to 25,413, with pressure stemming primarily from the financial, technology, and energy sectors.
Investor sentiment turned cautious again after stronger-than-expected US labor data raised the likelihood of the Federal Reserve hiking interest rates at its September meeting. The prospect of higher US interest rates weighs on risk assets across Asia—including Hong Kong stocks—as it can drive up yields and tighten global liquidity conditions.
Market attention is now shifting to China's trade data for August, due for release this week. The trade surplus is projected to widen to approximately US$120.1 billion, up from US$112.5 billion in July. This data will serve as a key indicator of external demand strength and the overall state of China's economy, potentially influencing the direction of Hong Kong stocks.
Technology stocks were a major source of downward pressure. Xiaomi fell about 3.2%, despite the company raising prices on several smartphone models and continuing its Class B share buyback program. Tencent Holdings weakened by around 0.8% and Meituan dropped 1.8%, while MiniMax also faced selling pressure. Conversely, Kingboard Laminates and Kingboard Holdings posted strong gains.
Today's decline marks a correction following a rally last Friday, when the Hang Seng surged approximately 1.7% to 25,651—its highest level since August 21. That earlier rise had been supported by a global rally in tech stocks and diminished expectations for a Fed rate hike, prior to the latest US labor report shifting market sentiment once again.
Newsmaker Analysis: The Hang Seng is facing renewed pressure after failing to sustain the upward momentum seen late last week. Expectations of a Fed rate hike are acting as a major drag on risk sentiment, while the market now looks to Chinese economic data for a fresh catalyst. If trade data indicates strong external demand, the possibility of a rebound remains open. Conversely, disappointing data could intensify pressure on the technology and financial sectors and cause the index to retest lower levels. (arl)
Source: Newsmaker.id